Break-Even Point Calculator for Any Business
Break-even units, revenue and contribution margin for any business, with presets for restaurants, food trucks, service businesses and landscaping.
Built by Toolsque Team · last updated September 17, 2026 · checked against our testing process
Your numbers
Running a coffee shop? Use the coffee shop break-even calculator, set up for cups per day.
Results
Every unit after 167 adds $30.00 of profit. To reach your target profit you need 234 units, about 8 per day.
Related: all finance calculators
How to use this break-even calculator
- Pick your business type: general, restaurant, food truck, service business or landscaping. It loads typical numbers and labels that you then replace with your own.
- Enter your monthly fixed costs: everything you pay even if you sell nothing: rent, salaries, insurance, subscriptions, loan payments.
- Enter your selling price per unit: what one customer pays for one product or service.
- Enter your variable cost per unit: what each sale costs you: materials, shipping, card processing fees, commissions.
- Optionally set a target profit: the calculator shows how many units you need to hit that profit, not just break even.
- Read the results: break-even units, break-even revenue, contribution margin, and a daily sales pace. Everything updates instantly as you type.
What is a break-even point?
Break-even analysis answers one question: how much do you have to sell before the business stops losing money. Your break-even point is the number of sales at which total revenue exactly covers total costs: you're not losing money, but not making any either. Every sale beyond it contributes pure profit. It's the single most useful number for pricing decisions, launch planning, and knowing whether a business idea is viable before you commit.
The break-even formula, explained
Break-even units = Fixed costs ÷ (Price per unit − Variable cost per unit)
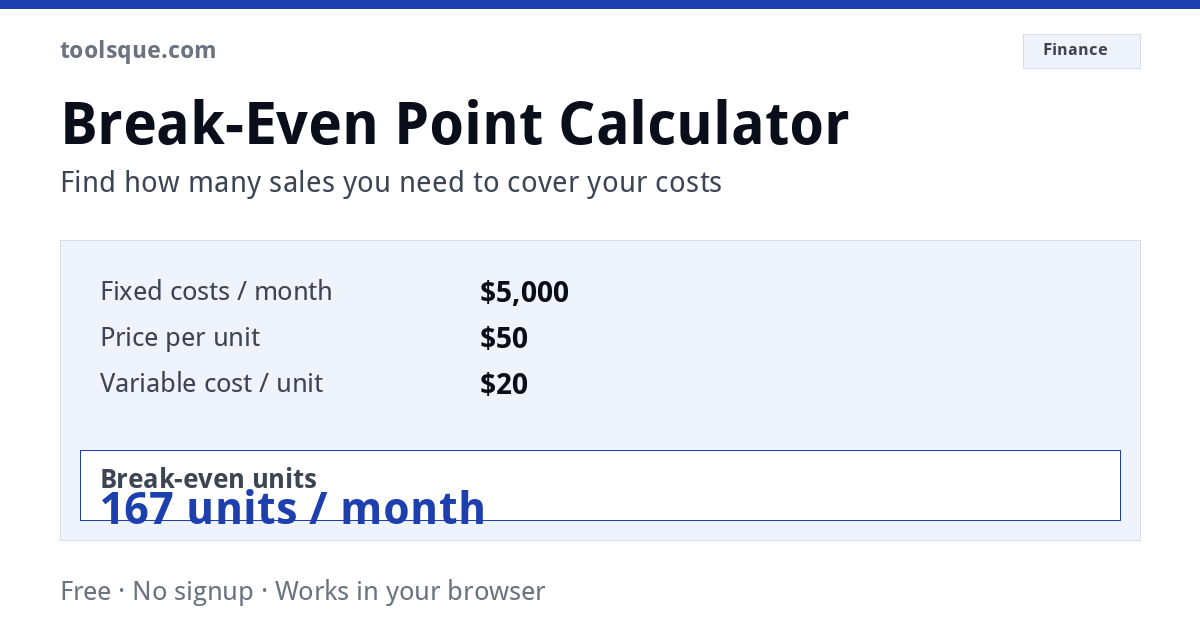
The bottom half of that formula, price minus variable cost, is your contribution margin: what each sale "contributes" toward covering fixed costs. If you sell a product for $50 that costs $20 to deliver, each sale contributes $30. With $5,000 in monthly fixed costs, you need 167 sales to break even (5,000 ÷ 30).
Fixed vs. variable costs: get this right
Fixed costs stay the same whether you sell 10 units or 1,000: rent, salaries, insurance, software subscriptions, equipment leases. Variable costs scale with each sale: raw materials, packaging, shipping, payment processing fees, sales commissions. Mixing these up is the most common break-even mistake: labor is fixed if staff are salaried, variable if you pay per job.
How to lower your break-even point
Three levers: raise prices (a 10% price increase often cuts break-even volume by 20 to 30% because it flows straight into contribution margin), cut variable costs (negotiate materials, switch processors), or cut fixed costs (sublease space, drop unused subscriptions). Run each scenario in the calculator above and watch the units number move.
Break-even by business type
The formula is the same for every business. What changes is what counts as one unit and which costs are fixed. Pick your business type in the calculator to load typical numbers, then replace them with your own.
Restaurant
Count one guest as one unit, called a cover. Fixed costs are rent, salaried staff, insurance, utilities and your POS and software. The price is the average check per guest including drinks, and the variable cost is food cost plus the hourly labor and card fees that rise with each guest. Full-service restaurants usually aim to keep food cost near 28 to 32% of sales.
Example: $28,000 of monthly fixed costs, a $24 average check and $8 of variable cost leave $16 per cover, so you need 1,750 covers a month, about 59 a day, to break even. Open the calculator set up for restaurants.
Food truck
Count one order as one unit. Fixed costs are the truck payment or lease, commissary kitchen fees, permits, insurance and a set fuel budget. The price is your average order value, and the variable cost is ingredients, packaging and card fees per order.
Example: $5,500 a month in fixed costs, a $12 average order and $4.50 of cost per order leave $7.50 per order. You need 734 orders a month to break even, about 25 a day if you trade every day, or more on the days you actually open. Open the calculator set up for food trucks.
Service business
Count one client or one project as one unit. Fixed costs are office or home office costs, software, insurance and any base salary, including a fair wage for yourself. The price is average monthly revenue per client, and the variable cost is the delivery hours, contractors and travel each client needs.
Example: $4,000 of fixed costs, $1,200 per client and $250 of delivery cost leave $950 per client, so 5 clients a month cover your costs. Service businesses with low variable costs, such as consulting, cleaning and IT support, often need very few clients to break even. Open the calculator set up for service businesses.
Landscaping or lawn care
Count one job or visit as one unit. Fixed costs are truck payments, insurance, equipment and storage. The price is the average invoice per job, and the variable cost is crew hours, fuel, materials and disposal for that job.
Example: $6,500 of fixed costs, $320 per job and $140 of cost per job leave $180 per job, so you need 37 jobs a month to break even. Recurring weekly or monthly contracts make that number far easier to hit than one-off jobs. Open the calculator set up for landscaping.
Running a coffee shop? The coffee shop break-even calculator works in cups per day. Planning a build-out? Pair this with the construction cost estimator, and once you are selling, the free invoice generator handles billing. Volume is only half the question. Once you know how many units you need, what it costs to generate that volume decides whether hitting the number is worth it.
The mistake that makes a break-even number useless
The most common error in break-even analysis is not a formula mistake. It is leaving the owner out of the costs.
If you run the business and take whatever is left at the end of the month, it is tempting to record no salary for yourself. The calculator then reports a break-even point that is genuinely achievable, and hitting it leaves you working full time for nothing. A business that breaks even while paying its owner zero has not broken even. It has quietly reclassified your wages as profit.
The fix is to decide what the job would cost to hire out, and put that figure into fixed costs before reading the result. The break-even number rises, sometimes uncomfortably, and it becomes the number that matters: the point at which the business covers its costs including the person running it.
Two related omissions are worth checking at the same time. Tax on profit is not a cost in this formula but it is a real claim on the money, so a break-even business has no tax problem while a profitable one should be reserving for it. And loan repayments are fixed costs that never appear on a profit and loss statement as such, which is why a business can look profitable and still run out of cash.
What the calculator does not account for
This tool calculates unit-based break-even using contribution margin per unit. It does not model blended margins across a product mix, step-fixed costs that jump at capacity thresholds, or time-to-break-even in months. If your fixed costs increase at 500 units (new equipment, additional staff), your real break-even is higher than the output shown.
Break-even as a pricing sanity check
Run the calculator in reverse: set target units, solve for required price. A 10% price increase on a product with 40% gross margin cuts required volume by roughly 20%. For food service numbers, pick Restaurant or Food truck in the calculator above.
What a step-fixed cost actually does to the number
The exclusions above mention step-fixed costs without explaining what they are, and it's worth understanding, because the calculator's single fixed-cost figure quietly assumes that number holds steady across every volume level, which real businesses often outgrow.
A step-fixed cost is one that's flat for a while, then jumps to a new flat level once you cross a capacity line, rather than rising smoothly. A single-location shop's rent stays fixed until you need a second location to handle more volume, at which point fixed costs jump in one step, not gradually. Same with staffing: one person handles order fulfillment up to a point, then you need a second, and payroll steps up all at once rather than creeping there.
This means break-even isn't always one clean number. It can be several, one per step. If 500 units is your current break-even but a new hire kicks in at 600 units to keep up with volume, the real break-even past that hire is higher than the smooth formula suggests, calculated fresh with the new fixed-cost figure. Run the calculator again with the post-jump fixed costs whenever you're planning growth that crosses one of those thresholds, rather than assuming the current number holds all the way up.
Treat this as a starting point. These figures are an estimate to help you plan. Your real numbers depend on your own costs, rates and terms, so check them against your actual books before you price anything on the result.
Frequently Asked Questions
What is the break-even point formula?
Break-even units = Fixed costs ÷ (Selling price per unit − Variable cost per unit). Break-even revenue = break-even units × selling price. This calculator does both automatically.
What is contribution margin?
It's your selling price minus your variable cost per unit: the amount each sale contributes toward covering fixed costs. Once fixed costs are covered, the contribution margin from each additional sale is profit.
What counts as a fixed cost?
Any cost that doesn't change with sales volume: rent, salaried payroll, insurance, software subscriptions, loan payments, equipment leases. If it shows up on your bank statement even in a zero-sales month, it's fixed.
Can I use this for a service business instead of products?
Yes: treat one "unit" as one client, one project, or one billable hour. Pick Service business in the business type menu and the labels and typical numbers switch to clients per month.
Is my data saved or sent anywhere?
No. The calculator runs entirely in your browser. Nothing you type is uploaded, stored, or tracked.
How do I calculate break-even for a restaurant?
Divide monthly fixed costs by the contribution margin per cover, which is the average check minus food cost and other per-guest costs. With $28,000 of fixed costs, a $24 check and $8 of cost per guest, you need 1,750 covers a month, about 59 a day.
How many orders does a food truck need to break even?
Fixed costs divided by profit per order. A truck with $5,500 a month in fixed costs and $12 orders costing $4.50 each needs 734 orders a month. Divide by the days you actually trade to get a daily target.
Should I include my own salary in fixed costs?
Yes. If you leave out a wage for yourself, the break-even point looks easy to reach but hitting it means working for free. Add what it would cost to hire someone to do your job, then read the result.